Historical report · observations from September 14, 2026
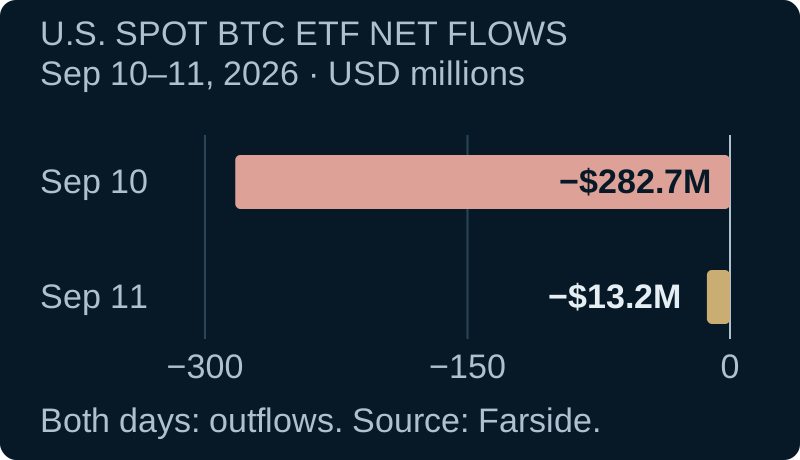
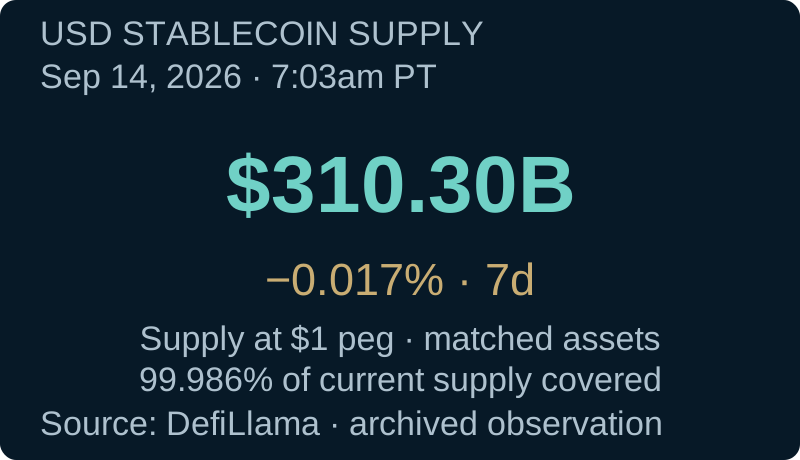
What changed ETF outflows eased; stablecoin supply stayed nearly flat.
Why BTC The price rebound still lacks broad liquidity confirmation.
What to watch Sustained fund inflows and expanding stablecoin supply would strengthen the demand picture.
Read the full analysis and sources
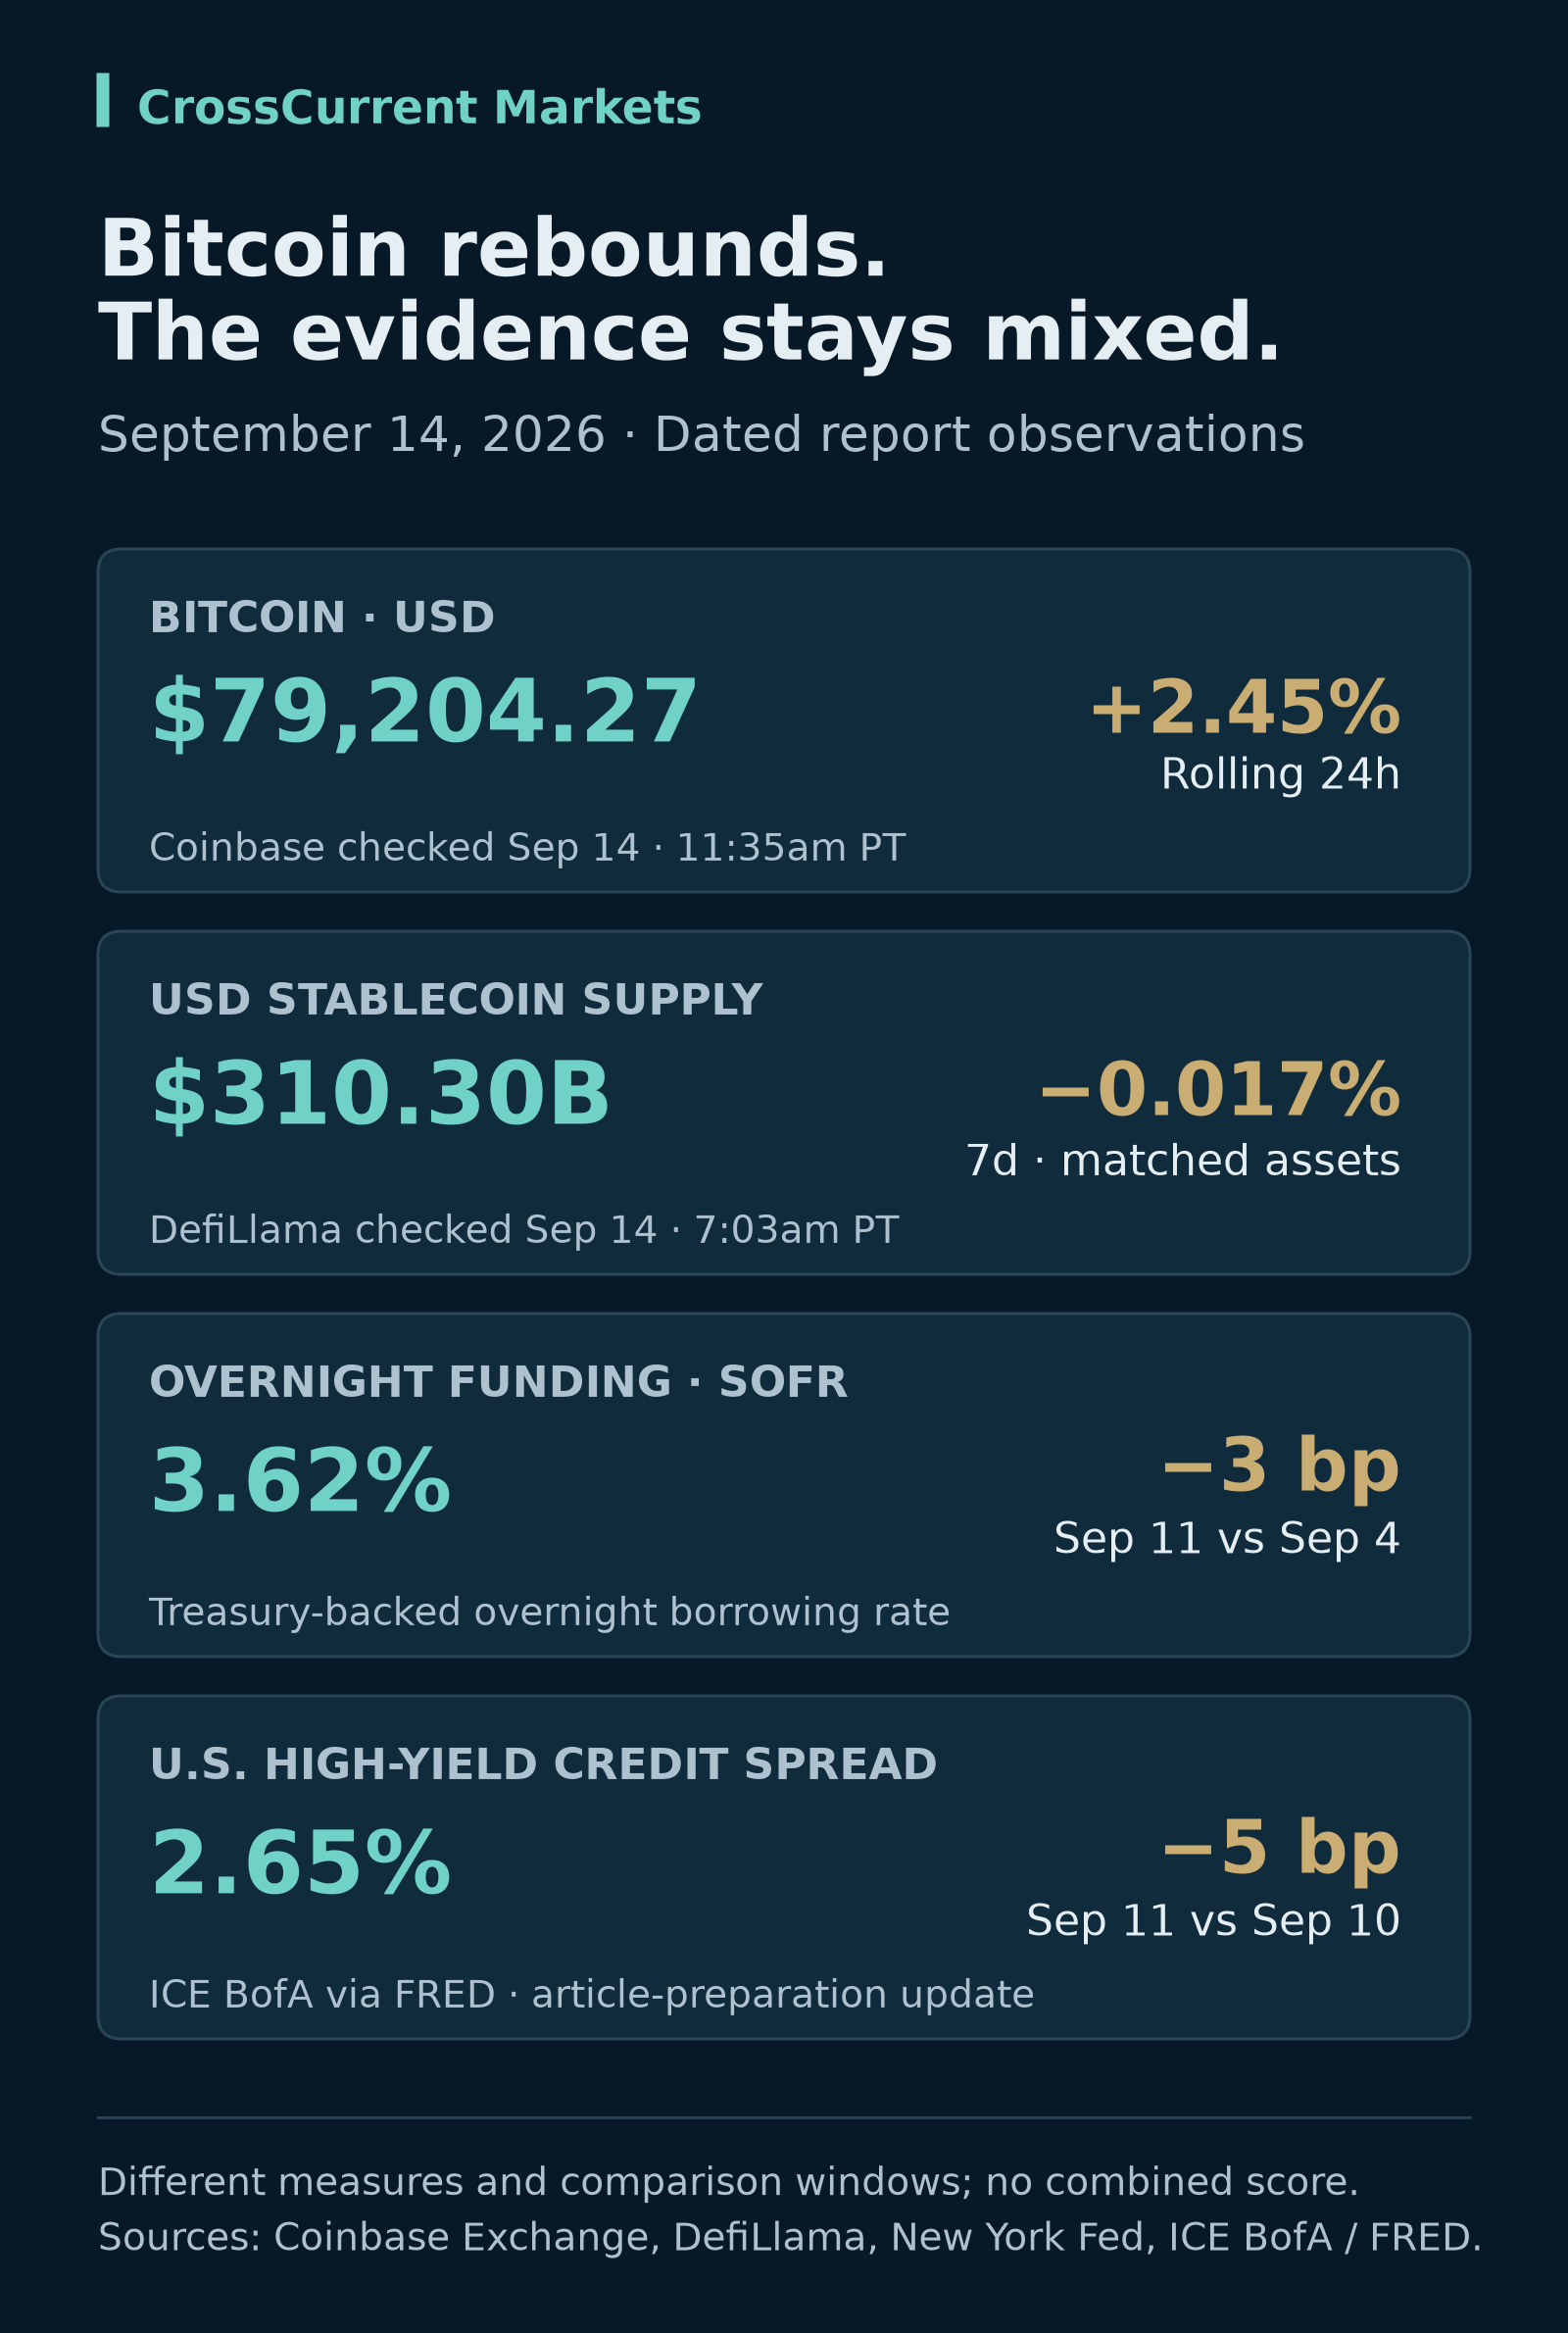
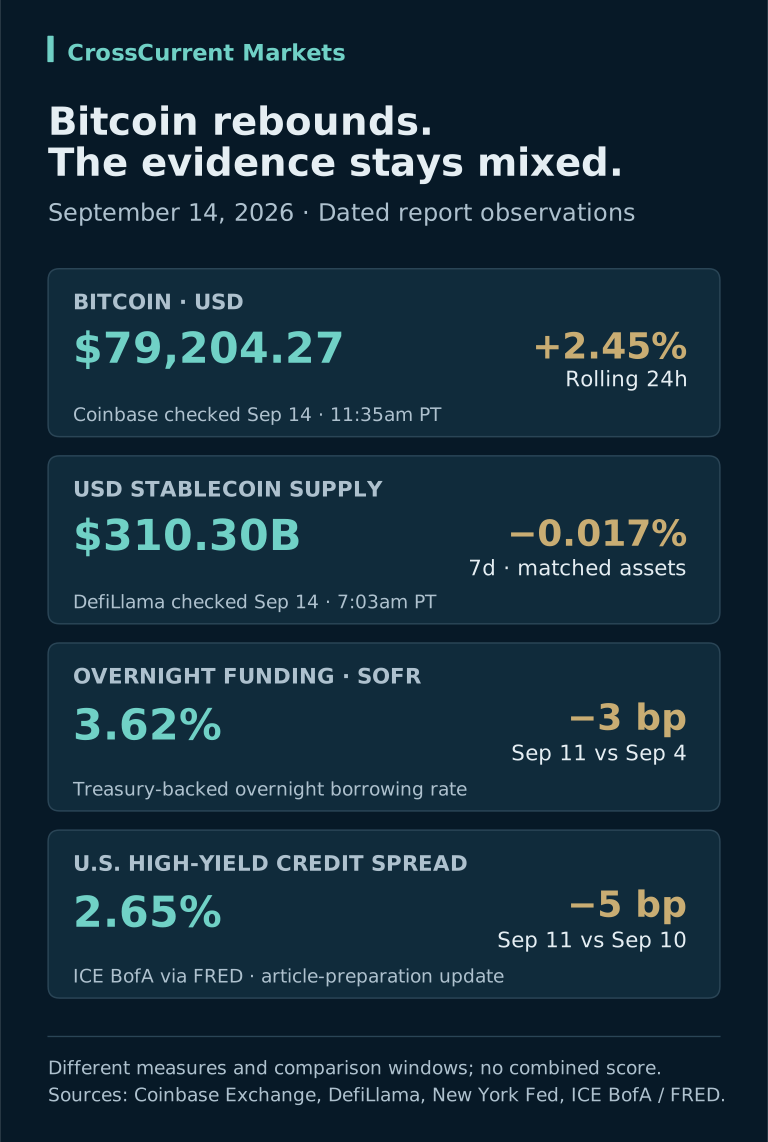
BTC $79,204.27 | +2.45% over the preceding 24 hours
Coinbase Exchange checked September 14 at 11:35am Pacific Time (PT).
Bitcoin was advancing at our late-morning price check, but the evidence behind the move was less uniform. Friday's U.S. Bitcoin ETF outflow was smaller than Thursday's, USD stablecoin supply was nearly unchanged over the week, and one measure of U.S. overnight funding costs had eased modestly. Meanwhile, the ECB (European Central Bank) had announced tighter policy, with the Federal Reserve's September decision still ahead.
Our assessment: the price rebound has limited confirmation from the liquidity measures in this report. There are supportive observations, but they do not yet establish a broad, synchronized improvement in funding and demand.
This report expands our September 14 X thread. Most observations come from the morning review completed by 7:12am PT. The 11:35am PT BTC quote and the credit-spread update below are identified separately. Periodic observations retain their own dates; the figures below are a dated research record, not live quotes.
The evidence across our eight market lenses
| Market lens | Evidence available in this report | Our reading |
|---|---|---|
| Global liquidity | U.S. weekly-average reserve balances rose $96.779B to $2,991.310B in the week ending September 9. Federal Reserve H.4.1 | A supportive U.S. balance-sheet observation; insufficient to establish a global liquidity turn. |
| Rates, dollar and credit | September 11 SOFR was 3.62%, down 3 basis points from September 4. A credit-data check during article preparation found a September 11 high-yield spread of 2.65%, down from 2.70% on September 10. New York Fed, ICE BofA spread via FRED | Funding costs and the credit spread eased in these comparisons, while the dated Treasury evidence below pointed to higher yields. |
| Stablecoin liquidity | Active USD stablecoin supply was $310.30B at our 7:03am PT check. The matched-assets seven-day change was −0.017%. DefiLlama data | Nearly flat supply offers little evidence of an expanding stock of dollar-linked tokens. |
| ETF and institutional flows | U.S. BTC ETFs recorded $13.2M of net outflows on September 11, versus $282.7M on September 10. Farside Investors | Outflows eased, but the sign remained negative. These flows do not identify all institutional activity. |
| Crypto market structure | BTC's share of CoinLore's tracked market capitalization was 60.57% at the 7:03am PT check. Deribit's BTC implied-volatility index, DVOL, closed its completed hourly candle beginning 6am PT at 37.90, versus 38.59 for the same hour the previous day. CoinLore, Deribit historical data | A dominance level and lower implied volatility do not establish broad participation or the cause of BTC's rise. |
| Capital rotation and AI | Nasdaq-100 closed 0.59% lower on September 11 than September 4. The gold observation in the morning review covered August, a different period. Nasdaq-100 via FRED | The available windows do not support a synchronized rotation comparison or a claim that AI investment pulled money from BTC. |
| Global macro and events | The ECB announced a 25bp increase, effective September 16. The Fed decision and August U.S. retail/restaurant sales release were still ahead. ECB decision, Fed calendar, Census calendar | Policy and incoming activity data could change rate expectations during the week. |
| Regulation and market access | The reviewed SEC material included its September 1 transfer-agent modernization proposal. SEC announcement | An existing proposal is context, not evidence of a new Monday regulatory catalyst or a final rule. |
Bitcoin is rising; demand confirmation remains incomplete
The opening BTC price and percentage change come from the same Coinbase Exchange rolling-24-hour statistics response. The price was $79,204.27, compared with that response's opening value of $77,312.33. This yields +2.45% after rounding. The time shown is when we checked the response; it is not a claim about the timestamp of an individual trade. Coinbase statistics documentation.
Our interpretation distinguishes the price move from evidence about its cause. A rising quote tells us that the asset traded higher over the stated window. Establishing whether the move reflects persistent investment demand, temporary positioning, or another influence requires additional observations.
The ETF comparison is encouraging relative to the previous day, but remains an outflow. Monday's fund-level entries were unreported at the research cutoff, so no Monday total belongs in this assessment. A placeholder zero would give a misleading impression of a completed observation. Farside's daily table.
Stablecoin supply offers a separate view. Our calculation sums active USD-pegged circulating assets at their dollar peg. It includes current balances even when an asset lacks usable weekly history; the percentage comparison uses only assets with both current and prior-week values. In this snapshot, 309 of 312 assets qualified for that comparison, representing 99.986% of current supply. The result was almost flat, rather than a meaningful expansion. DefiLlama source data.
Supply does not reveal how those tokens are being used. Existing stablecoins could change hands or be deployed into BTC while aggregate supply barely moves. Conversely, a larger supply would not prove that its holders intended to buy Bitcoin. We therefore read ETF flows, stablecoin balances and price as different pieces of evidence.
Funding conditions offer support, with important differences in timing
SOFR—the Secured Overnight Financing Rate—measures the cost of overnight cash borrowing backed by U.S. Treasury securities. Its September 11 reading of 3.62% was unchanged from September 10 and below the 3.65% reading on September 4. The effective federal funds rate was 3.63%, within the 3.50–3.75% target range reported for that date. New York Fed rate observations, SOFR definition.
The distinction is useful: a market funding rate can move while the policy target remains unchanged. Our reading is modest easing in this particular funding measure, not a Federal Reserve rate cut.
The weekly reserve increase provides another supportive observation. In the same H.4.1 weekly-average comparison, the Treasury General Account—the Treasury's account at the Fed—fell by $84.600B. These are averages for the week ending September 9, not balances measured at the time of today's BTC quote. September 10 H.4.1 release.
The counterweight is that the morning's retrieved Treasury table showed September 10 two-year and ten-year yields at 4.56% and 4.95%, up from 4.43% and 4.83% on September 9. The latest dollar observations retrieved were older still, through September 4. Neither source supported a claim about live Monday yields or foreign exchange. Federal Reserve H.15, Federal Reserve H.10.
Credit-data update during article preparation: FRED now displayed the ICE BofA U.S. High Yield option-adjusted spread at 2.65% for September 11, compared with 2.70% on September 10. That is a decline of 5 basis points. This measures a yield spread for the included below-investment-grade corporate bonds relative to the Treasury curve, after adjusting for embedded options. Our reading is additional evidence of easier conditions in that credit measure, without ruling out stress elsewhere. The morning research record had retained the older September 10 observation; this article identifies the newer value explicitly. ICE BofA series and definition via FRED.
Taken together, these observations argue for checking each channel separately. We have not added weekly reserve averages, daily funding rates and market prices into a single liquidity score.
The policy calendar is the next test
The announced 25bp increase belongs to the ECB, which set its deposit rate to become 2.50% on September 16. At this report's cutoff, the Fed's September decision had not occurred. Treating the two decisions as the same event would misstate both the institution and the timing. ECB announcement.
Our focus around the Fed is the combination of the decision, projections and guidance, followed by the response of funding markets, Treasury yields and the dollar. A policy headline alone will not settle the BTC outlook.
| Scheduled event | Pacific date and time | What we will examine |
|---|---|---|
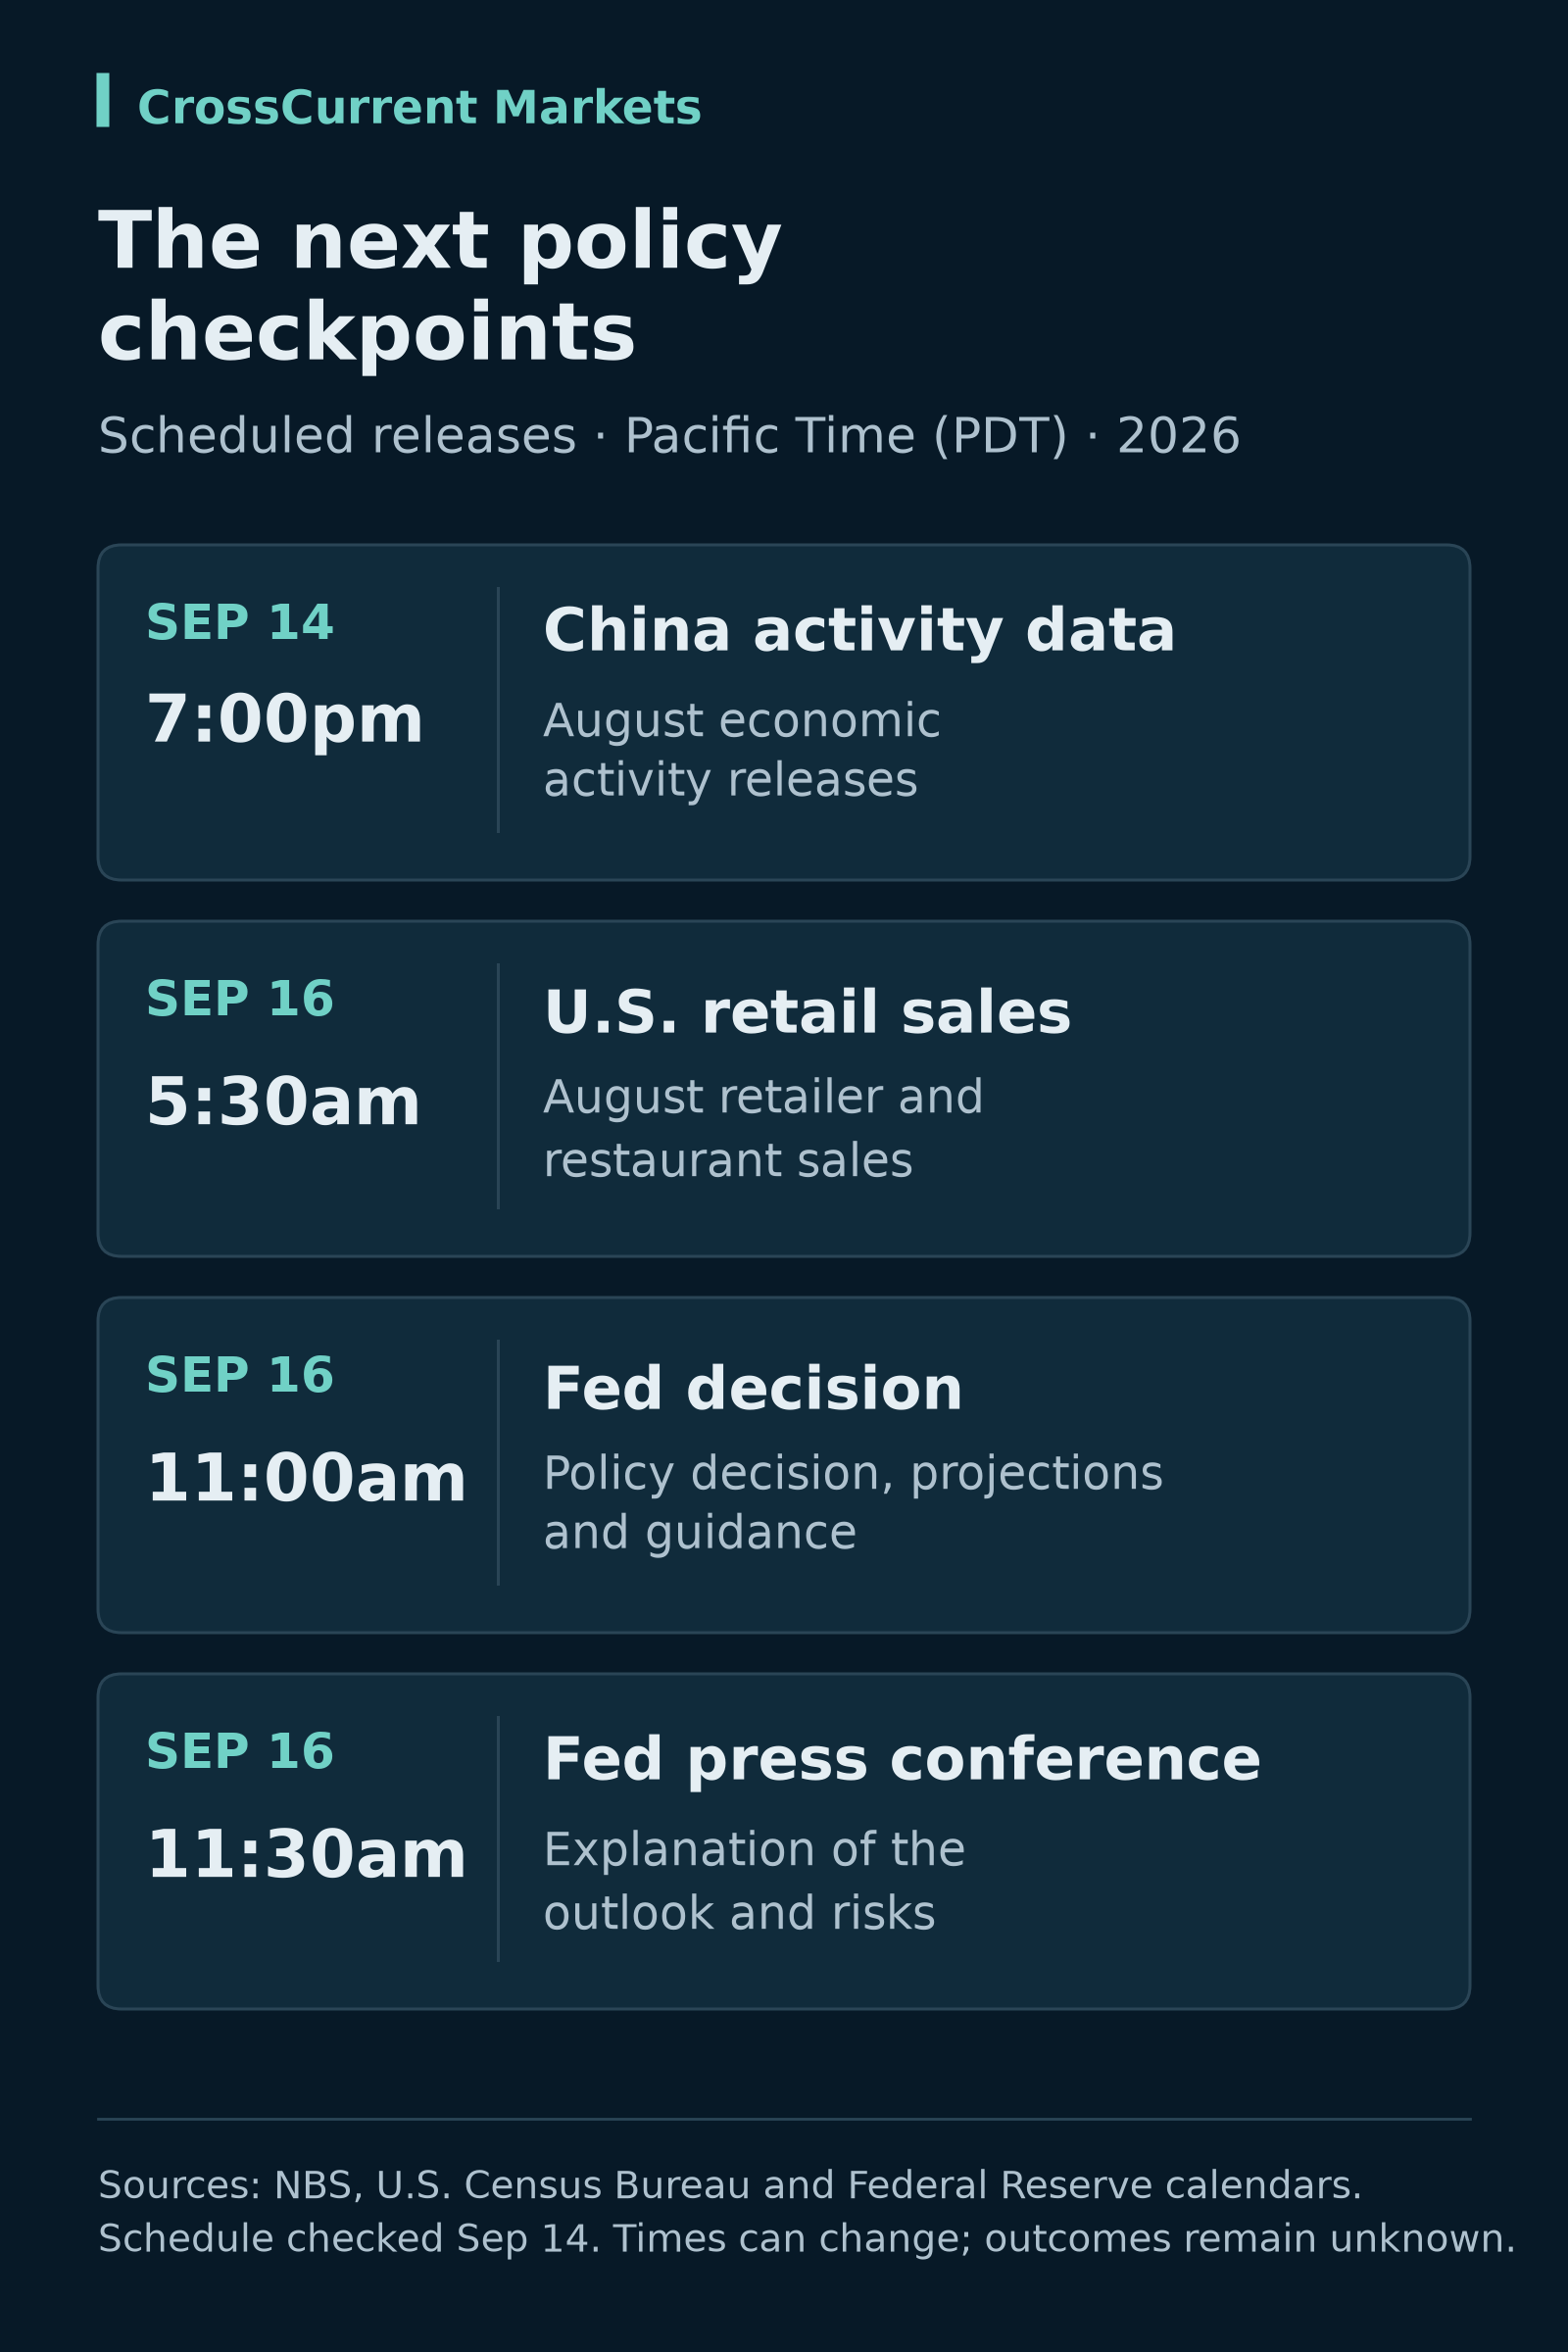
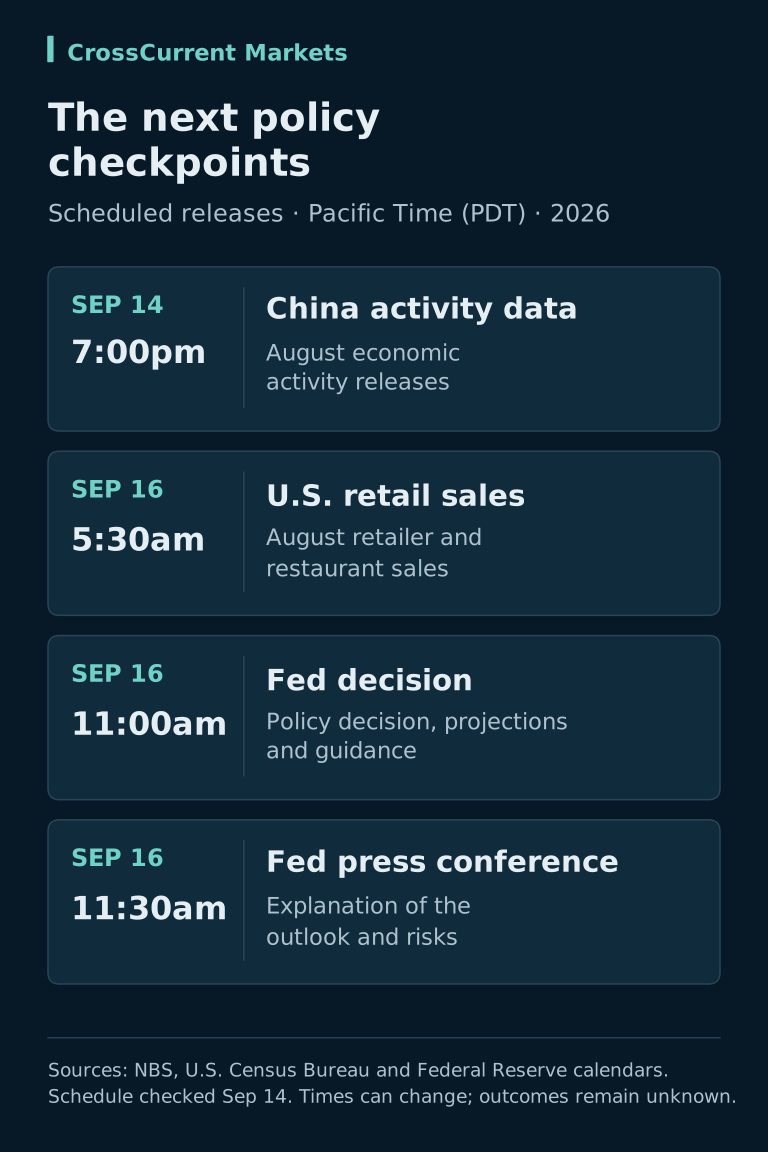
| China August activity releases | September 14, 7:00pm PT | New activity evidence; this corresponds to the following morning in Beijing. NBS calendar |
| U.S. August retail and food services sales | September 16, 5:30am PT | Sales at retailers and restaurants, including the composition of the change and revisions. Census calendar |
| Federal Reserve decision | September 16, 11:00am PT | The policy decision, projections and accompanying explanation. Fed calendar |
| Federal Reserve press conference | September 16, 11:30am PT | Clarification of the outlook and risks. Fed calendar |
“Retail sales” here means the Census Bureau's monthly report on U.S. retail and food services sales. It measures dollar spending in those categories; the headline is adjusted for seasonal effects, but not price changes. A stronger dollar total therefore does not automatically mean an equal increase in the quantity purchased. Census sales report and definitions.
Our interpretation is that the release could alter views of consumer demand and the interest-rate outlook. The effect on BTC would depend on the wider response, including whether bond yields, the dollar and risk appetite reinforce or offset the initial reading. Scheduled times are not release confirmations.
What would strengthen or weaken our assessment?
More supportive evidence would include subsequent complete ETF sessions showing sustained inflows, expanding comparable stablecoin supply, and easing funding conditions that persist beyond a single observation. These would improve the case for broader support behind price, without proving that every channel was driving the same move.
A less supportive combination would be renewed ETF outflows alongside contracting stablecoin supply, rising funding costs or tighter credit conditions. Policy communication that raised expected borrowing costs would add another question for the rebound.
We also need better coverage before drawing some conclusions. The morning on-chain response failed an internal consistency check and was excluded. A single derivatives open-interest snapshot could not establish a positioning trend. Current global liquidity, comprehensive regional monetary data and a synchronized cross-asset comparison were unavailable. Those gaps remain gaps; they are not neutral readings.
This is public-source market commentary, not a model-generated regime assessment or a BTC price target. We will evaluate subsequent evidence against the dated observations here and retain any corrections with their dates.
For the underlying definitions, see our signal library, stablecoin liquidity guide and rates, dollar and credit guide.
Informational research; not personalized investment advice.
Archived report · September 14, 2026. Values retain their original dates.